
A vehicle can enter a collision center with damage that appears repairable at intake and become a total loss after teardown, parts pricing, scanning, and calibration requirements are documented. The repairable versus total loss decision is no longer driven by visible panel damage alone. For repairers, insurers, recyclers, and towing operators, it has become a moving calculation shaped by repair economics, vehicle technology, and the quality of information available early in the claim.
Repairable Versus Total Loss Is an Economic Decision
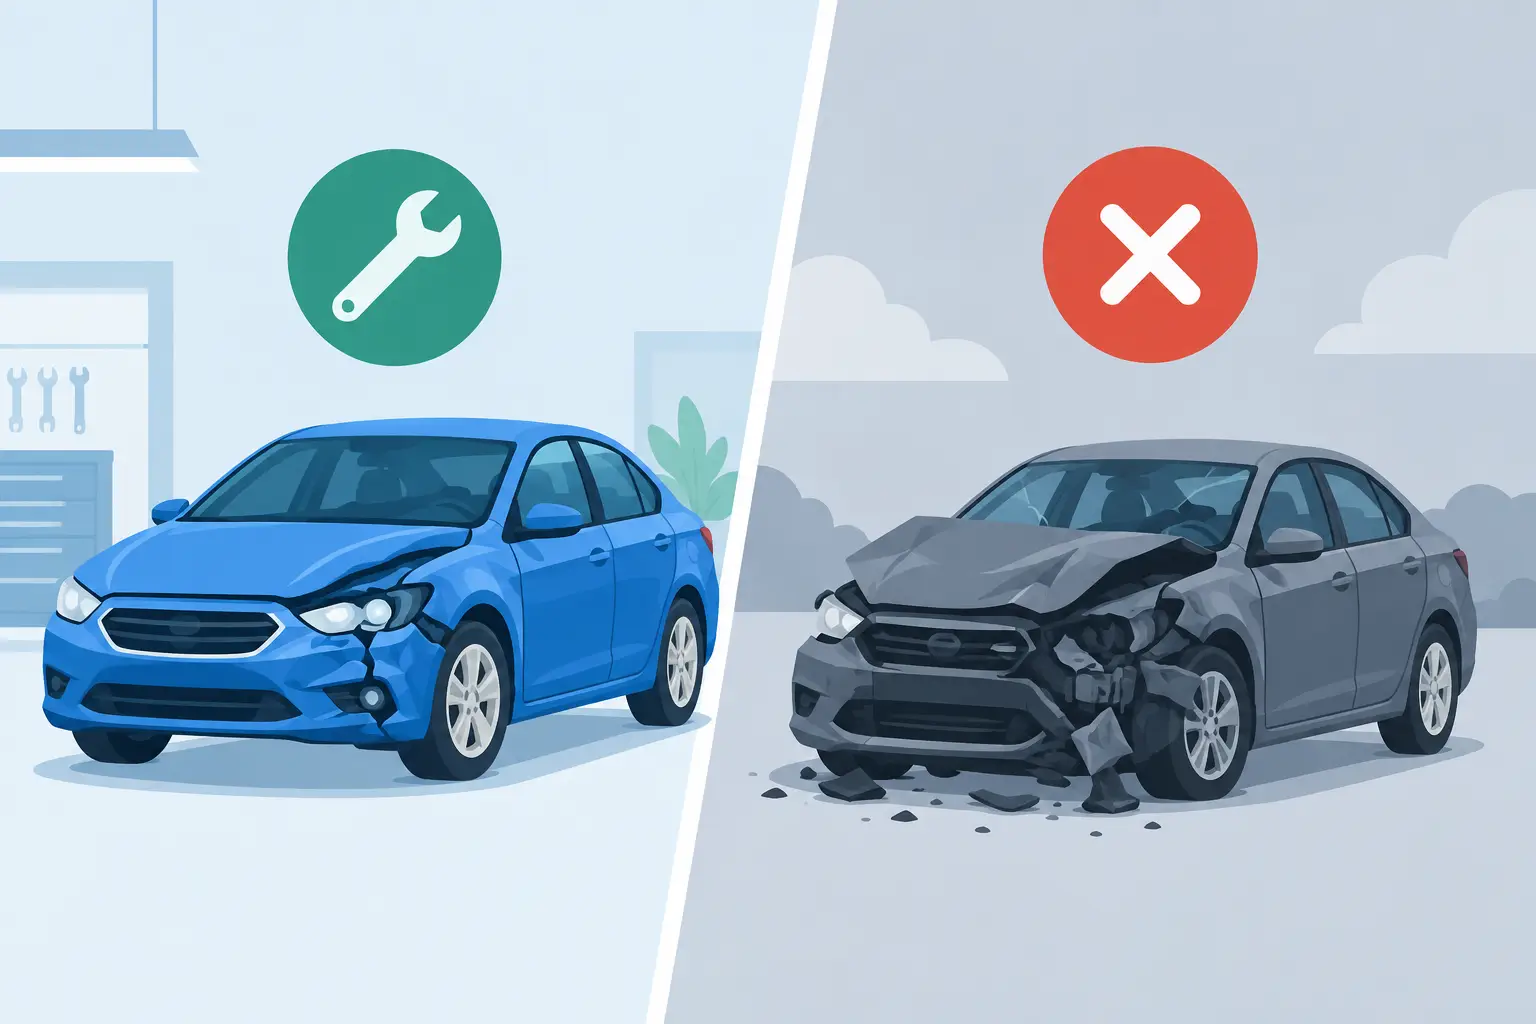
A total loss is generally an economic determination, not a declaration that a vehicle cannot be repaired. A late-model vehicle with extensive structural or battery damage may be technically repairable, yet still exceed the carrier’s projected cost threshold. Conversely, an older vehicle with relatively modest damage may total because its actual cash value cannot support a conventional repair plan.
State regulations, insurer guidelines, policy language, title branding rules, taxes, fees, rental exposure, and salvage return all affect the calculation. Many carriers use a total loss threshold, while others apply a total loss formula that compares repair cost plus salvage value against actual cash value. The exact methodology varies by jurisdiction and insurer, but the operating reality is consistent: a repair plan is competing against a vehicle’s pre-loss value and its expected salvage proceeds.
That distinction matters for collision operators. A repair estimate is not simply a production document. It is evidence in a financial decision that can redirect a vehicle out of the repair pipeline at any point. When a file changes status after a supplement, the shop may lose expected labor and parts revenue while retaining administrative time, teardown work, storage exposure, and a dissatisfied vehicle owner who believed repairs were underway.
For insurers, inconsistent early decisions can create avoidable cycle time, rental expense, and customer friction. For recyclers, higher total-loss volume can increase salvage supply, although recoverable component quality and demand by model mix determine whether that volume translates into stronger returns.
Why Early Estimates Miss the Full Cost
The first estimate is often prepared before the vehicle has been fully disassembled, scanned, measured, or researched for repair procedures. That creates a predictable gap between visible damage and final repair cost. The gap has widened as vehicles add more sensors, electronic modules, high-strength steels, aluminum structures, advanced lighting, and integrated safety systems.
A bumper impact can now involve radar brackets, blind-spot sensors, parking sensors, active grille shutters, headlamp assemblies, wiring, and post-repair calibration. A wheel strike can introduce suspension damage, alignment requirements, steering-angle sensor procedures, and ADAS calibration. What looked like a straightforward body repair can become a multi-department repair event involving mechanical work, diagnostics, sublet coordination, and OEM procedure review.
Parts availability adds another variable. An estimate may assume an aftermarket or recycled component that later proves unavailable, unacceptable under the carrier’s parts policy, or unsuitable for the repair procedure. A price increase on an OEM lamp, radiator support, airbag component, or electronic module can materially change the repair-to-value ratio. So can backorder delays that extend rental days and raise the carrier’s overall indemnity exposure.
Diagnostics and calibrations have changed the threshold conversation
Pre-repair and post-repair scans are now routine line items in many repair plans, but the larger cost question is what the scan reveals. Fault codes may identify prior damage, impact-related module failures, or conditions requiring further diagnosis. A calibration is not merely an add-on operation when a vehicle’s procedure requires it. It is part of returning the safety system to its intended performance.
For shop managers, the operational challenge is documentation. The repair plan needs a clear connection between damage, OEM requirements, diagnostic findings, and the labor or sublet operation billed. Weak documentation can delay authorization. Strong documentation improves the odds that all stakeholders recognize the true cost before a vehicle is deep into production.
Electric vehicles add another layer. Battery enclosure damage, high-voltage isolation concerns, coolant-system exposure, and manufacturer restrictions can quickly change repairability. Even where the battery is not directly damaged, a qualified assessment may require specialized training, tooling, isolation procedures, and transport controls. A vehicle can be repairable, but not economically or operationally appropriate for every facility.
The Operational Cost of a Late Total Loss
A late total-loss decision consumes capacity that a repairable vehicle could have used. The vehicle occupies a space, requires blueprint labor, may generate parts orders and returns, and often triggers repeated conversations among the shop, appraiser, insurer, customer, lender, and salvage vendor. In a high-volume environment, those interruptions have a real throughput cost.
The impact is especially acute for multi-shop operators tracking touch time, estimate-to-delivery performance, and technician utilization. If total-loss candidates are not identified quickly, production teams may begin work before the claim economics are settled. That can leave technicians waiting for revised approvals or force managers to reshuffle schedules after a vehicle exits the repair plan.
There is also a customer-experience risk. Consumers generally do not distinguish between a technical repairability assessment and an insurer’s financial total-loss decision. They see a vehicle that was initially described as repairable, then declared a loss after several days or weeks. The repair facility may not control the decision, but it still absorbs much of the communication burden.
Towing and storage providers face parallel pressures. Delays in appraisal, owner contact, lien processing, or salvage assignment can keep total-loss units on a yard longer than expected. Clear handoffs and status visibility matter because storage exposure can become a point of dispute across the claims chain.
Building a Better Early Decision Process
The objective is not to total more vehicles or to push marginal repairs through production. It is to reach a defensible decision sooner, with sufficient technical detail to avoid reversals. That requires claims and repair operations to treat early damage assessment as a cross-functional process rather than a quick visual estimate.
Four practices can improve decision quality and reduce late-file disruption:
- Prioritize teardown on likely total-loss candidates. High-severity impacts, airbag deployment, structural displacement, wheel damage, flood exposure, and EV battery-area impacts warrant early investigation rather than a preliminary cosmetic estimate.
- Verify value and salvage assumptions early. Actual cash value, trim level, options, mileage, prior condition, and local salvage demand can materially alter the outcome. An inaccurate valuation can send a repairable vehicle to salvage or authorize a repair that will not remain viable.
- Document procedure-driven operations before authorization. OEM repair information, scan results, calibration needs, structural measurements, and required component replacements should be visible in the file early enough to inform the total-loss review.
- Create escalation rules for estimate movement. Shops and carriers benefit from defined triggers when supplements exceed a set dollar amount, when parts change from recycled or aftermarket to OEM, or when rental exposure begins to alter the economics.
Technology can help, but it does not eliminate the need for judgment. Image estimating and AI-assisted damage detection may improve triage and estimate consistency, particularly for visible damage. They are less reliable when the key costs are hidden behind trim, tied to repair procedures, or dependent on component availability. A disciplined blueprinting process remains the strongest control against false early certainty.
Claims Economics Will Keep Raising the Stakes
The repairable-versus-total-loss balance will continue to shift with used-vehicle values, interest rates, parts inflation, salvage pricing, labor rates, and vehicle complexity. A change in any one input can affect thousands of claim decisions across a carrier’s portfolio. That makes total-loss management a broader business issue than a single-file estimating exercise.
For repair networks, the strategic question is whether their intake, blueprinting, diagnostics, and communication processes provide enough early clarity to protect capacity. For insurers, it is whether claim workflows capture the true repair scope before rental and handling costs compound. For recyclers, it is whether changing total-loss volume creates usable inventory in the categories their buyers need.
The strongest operators will treat early repairability assessment as a capacity-management discipline. The better the first complete picture of a vehicle’s condition, the sooner every business in the claim can commit resources to the right outcome.