
Market Intelligence
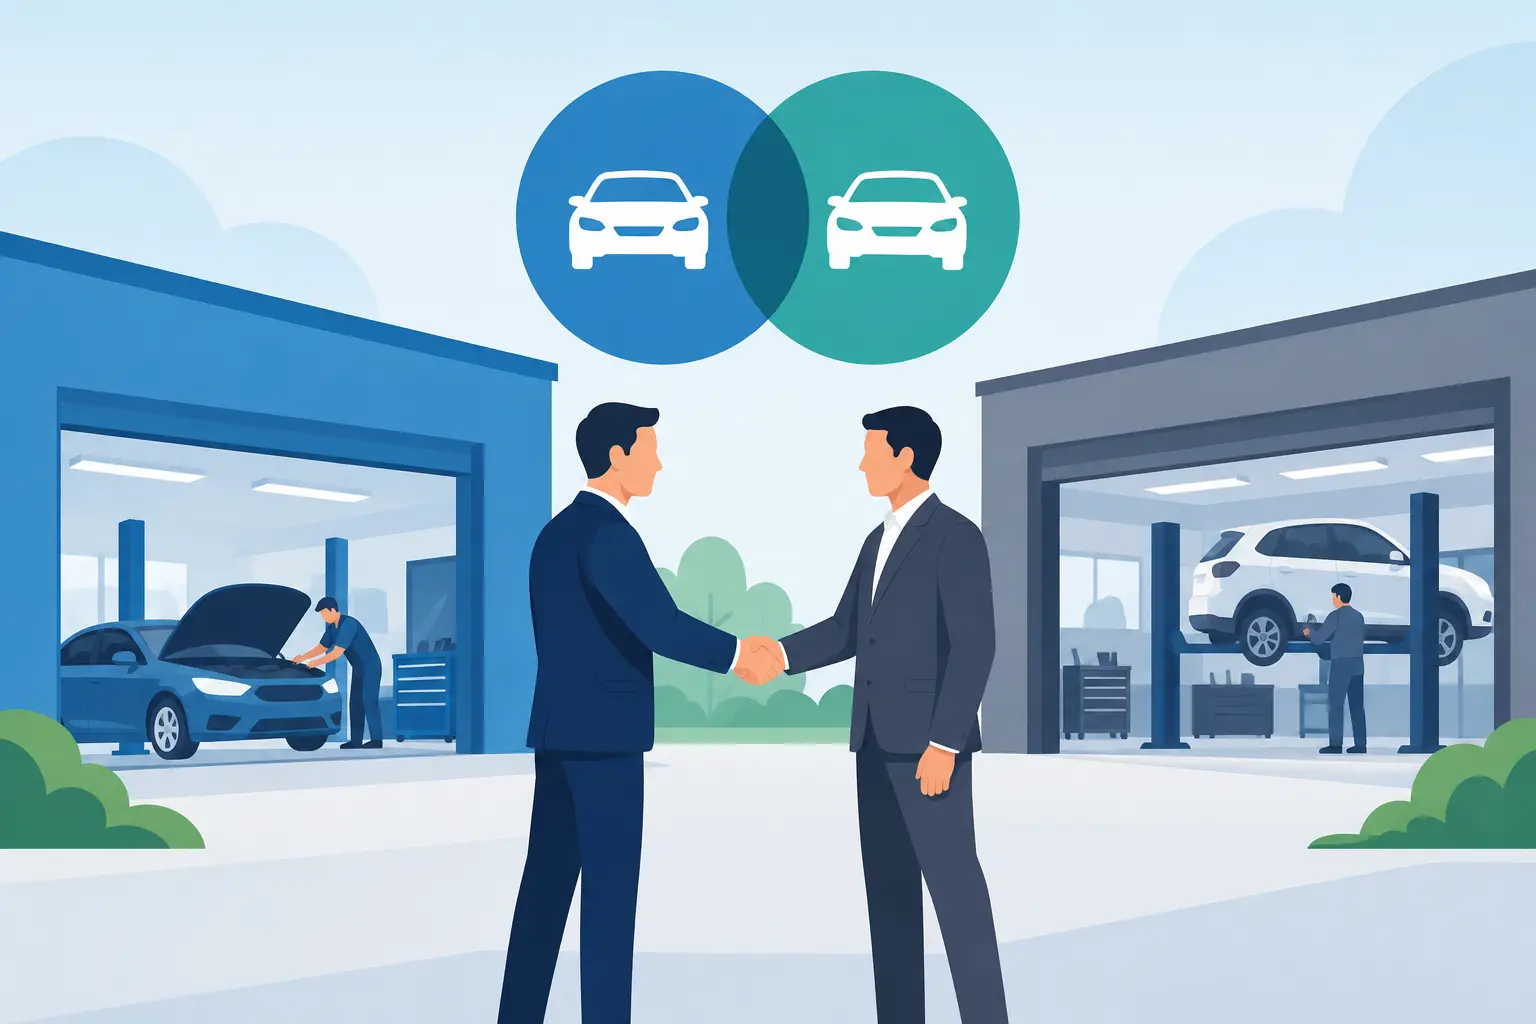
A repair business can feel the effect of a merger long before a new logo appears on the building. Parts purchasing may move to a national agreement, insurer scorecards may be standardized, estimating systems may change, and regional managers may begin measuring cycle time against a wider network. The automotive mergers outlook matters because consolidation is no longer confined to the largest collision MSOs or publicly traded parts companies. It is reshaping who controls capacity, customer access, repair data, and purchasing leverage across the North American service ecosystem.
For operators, the useful question is not whether M&A activity will continue. It will. The more practical question is which assets remain strategically valuable when capital is more selective, repair complexity is rising, and buyers must prove that an acquisition can improve operating performance rather than simply add revenue.
Automotive Mergers Outlook: Deal Logic Is Changing
The era of buying locations primarily to build a larger map has given way to a more disciplined acquisition environment. Scale still matters, particularly in collision repair, parts distribution, tire retail, towing, and diagnostic services. But buyers are placing greater weight on integration readiness, market density, technician retention, insurer relationships, and the condition of the acquired business’s operating data.
That shift favors businesses that can show repeatable execution. A single repair facility with strong labor productivity, dependable customer-pay volume, calibrated ADAS procedures, and stable local leadership can be more attractive than a larger operation with uneven margins and undocumented processes. In collision repair, a buyer may value a location differently depending on its DRP mix, OEM certifications, repair-planning discipline, sublet dependence, and proximity to existing network capacity.
Higher financing costs have also changed the math. Financial sponsors and strategic acquirers are still pursuing platform and tuck-in opportunities, but they have less room to absorb underperforming locations or prolonged integration problems. Sellers expecting valuation multiples based only on pandemic-era growth or broad consolidation headlines may encounter a more rigorous underwriting process. Quality of earnings, normalized labor costs, equipment obligations, lease terms, and deferred facility maintenance receive more scrutiny.
Collision Capacity Remains a Strategic Asset
Collision repair remains a central consolidation story because insurers need reliable repair capacity in markets where severity, parts delays, and technician shortages can extend cycle times. A well-run regional MSO offers something more valuable than a collection of bays: it provides a managed production system with measurable performance across estimating, repair planning, parts, body, paint, calibration, and customer communication.
Insurer relationships can strengthen the case for a transaction, but they are not a substitute for operational discipline. DRP volume may be concentrated, contractual terms can change, and carrier assignments do not eliminate pressure on cycle time, touch time, supplement control, or CSI. Buyers will increasingly test whether a target can maintain repair quality and throughput as vehicle complexity raises both labor content and administrative burden.
The same dynamic affects independent operators deciding whether to sell, partner, or remain independent. Consolidation can provide purchasing programs, centralized finance, recruiting support, and technology investment. It can also reduce local discretion over staffing, vendor selection, pricing practices, and capital spending. The right decision depends on the owner’s succession plan, market position, balance sheet, and willingness to standardize operations.
Mechanical, Parts, and Technology Deals Follow Different Signals
The automotive mergers outlook is broader than collision. Mechanical repair consolidators are looking for density in attractive local markets, recurring maintenance demand, and credible store-level management. Their challenge is that labor availability, shop productivity, and customer retention can vary sharply by location. A multi-store footprint without consistent service advisor practices or technician depth may be difficult to integrate.
In parts distribution, the strategic value of scale rests on inventory availability, route density, commercial account retention, and purchasing power. Consolidation can improve distribution economics, but it can also expose weaknesses in catalog accuracy, returns processing, warehouse labor, and last-mile delivery performance. Repairers should watch these transactions closely because supplier changes can alter order cutoffs, fill rates, credit terms, and local account support.
Diagnostic, calibration, software, and data businesses are also likely to remain active M&A targets. These companies sit near a growing pain point for repairers: converting increasingly complex vehicle information into safe, documented, billable repair procedures. Yet technology acquisitions carry their own integration risks. A broader platform is useful only if it reduces duplicate entry, supports repair workflows, and delivers usable support at the shop level. Adding another portal is not a productivity strategy.
What Consolidation Changes Inside a Repair Business
A merger can create operational benefits that are tangible: stronger vendor negotiations, shared training resources, centralized recruiting, capital for equipment, and more consistent reporting. For a growing independent, a larger organization may also create clearer career paths for technicians, painters, estimators, and managers. That matters in a labor market where advancement opportunities can influence retention as much as hourly pay.
The trade-off is standardization. Centralized purchasing may lower costs but limit a manager’s ability to use a local supplier who solves urgent parts problems. Common estimating or management systems can improve visibility but require retraining and disciplined adoption. Centralized KPIs can identify underperformance, but poorly designed scorecards can encourage speed at the expense of repair planning, documentation, or employee engagement.
Integration is where deal value is either protected or lost. Leaders should expect close attention to scheduling, parts procurement, repair-status communication, payroll practices, workflow roles, and financial controls. These are not back-office details. In a collision operation, a change in who orders parts or approves supplements can affect keys-to-keys time, rental expense, technician efficiency, and insurer relationships within weeks.
Due Diligence Is Becoming More Operational
Buyers are increasingly reviewing the systems behind a shop’s financial results. EBITDA still drives valuation discussions, but it does not explain whether earnings are durable. A strong diligence process examines labor gross profit by department, technician utilization and proficiency, parts margin quality, supplement frequency, sublet spending, customer-pay retention, and capital needs for lifts, scan tools, calibration equipment, paint booths, or facility upgrades.
For sellers, this means preparation should begin well before a letter of intent. Clean financial statements matter, but so do documented SOPs, current OEM credentials, lease assignments, environmental compliance records, vendor agreements, and credible management depth. A business that relies entirely on an owner’s personal insurer relationships or undocumented judgment may still sell, but it will be harder to position as a scalable operating asset.
For buyers, the concern is not just finding cost synergies. It is determining whether a target’s local reputation and employee base will survive the transition. In many service businesses, technicians and front-office leaders are the assets that make the revenue possible. A deal model that assumes labor retention without addressing compensation, culture, training, and communications is incomplete.
Where Automotive Mergers May Stall
Not every market can support the same consolidation playbook. Local antitrust attention may become more relevant where a transaction materially concentrates collision capacity, towing coverage, parts supply, or other essential services. Even when a transaction clears regulatory review, insurers, fleet accounts, and consumers may react differently if fewer providers control a local market.
Valuation expectations can also slow transactions. Owners who built profitable businesses over decades may view a sale as recognition of personal effort, while buyers evaluate future cash flow after accounting for rent resets, equipment purchases, wage pressure, and integration costs. The gap is often emotional as well as financial.
Technology can complicate transactions too. Shops that have delayed investment in scan tools, ADAS calibration access, estimating infrastructure, cybersecurity, or technician training may require significant post-close capital. Conversely, a highly equipped operation may still face a weak return if its workflow does not consistently convert technical capability into documented, paid repair procedures.
Automotive Mergers Outlook: Operating Priorities
Whether a business is likely to buy, sell, partner, or remain independent, the operating response is similar: know what creates value in your market and measure it consistently. Repair leaders should be able to explain where their volume comes from, which relationships drive it, how much capacity is truly usable, and where profit leaks from the process. That explanation needs to be supported by clean numbers, not anecdotal confidence.
Owners should also distinguish scale from strength. Adding locations, service lines, or vendor programs can expand a business, but only disciplined repair planning, productive labor, controlled parts processes, and credible customer communication produce durable returns. For independent facilities, improving those fundamentals is not merely preparation for a potential sale. It is the clearest way to preserve bargaining power when larger competitors enter the market.
The businesses best positioned for the next phase of consolidation will be those that can show, day after day, that their capacity is safe, measurable, profitable, and difficult to replace.